

I. Gold Tests Near $4244 on Thursday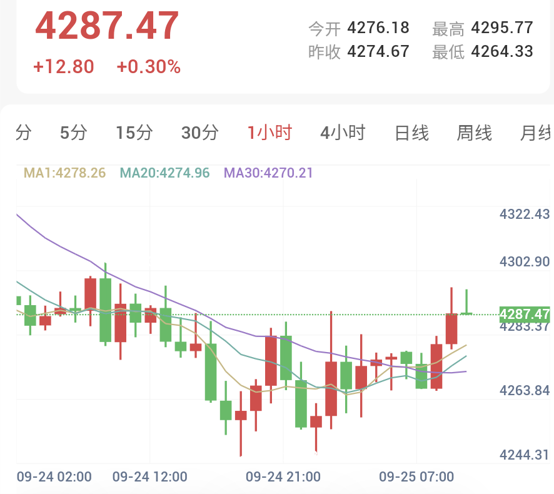
Gold markets remained under pressure on Thursday, with spot gold touching an intraday low of $4,244.16 per ounce—its lowest level since September 16—before recovering some losses to settle at $4,274.58 per ounce, down approximately 0.3% on the day.
A major market disruption came from the Middle East. A Saudi-led coalition stated that it intercepted six ballistic missiles launched by the Houthi movement targeting Taif and the Red Sea coastal region of Yanbu.
This news quickly heightened market concerns over regional supply security. Benchmark energy contracts surged nearly 5% intraday, with European benchmark energy contracts closing 3.4% higher to mark their highest closing level since September 15.
II. Fed Officials Deliver Coordinated Hawkish Remarks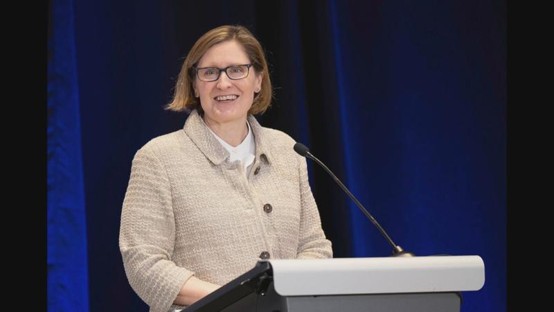
Persistent hawkish signals from Federal Reserve officials provided another key backdrop for gold's latest correction.
Philadelphia Fed President Paulson stated on Thursday that US inflation remains "stubbornly high" and that a moderate further tightening of policy could be appropriate if economic conditions evolve as expected. She added that she would support a policy path that guides inflation back to the 2% target. New York Fed President Williams echoed this sentiment, noting that it is a reasonable judgment that the Fed may need to raise rates again before the end of 2026, though final decisions will depend on incoming economic data. The Fed raised its policy rate band by 25 basis points to 3.75%-4.00% in September, with 16 out of 18 policymakers previously projecting at least one more rate hike this year.
CME FedWatch tools show that market expectations for another rate hike in October remain elevated. Continuous policy expectation shifts keep gold in a sensitive short-term phase.
III. Dollar Climbs to 2-Month High as Treasury Yields Advance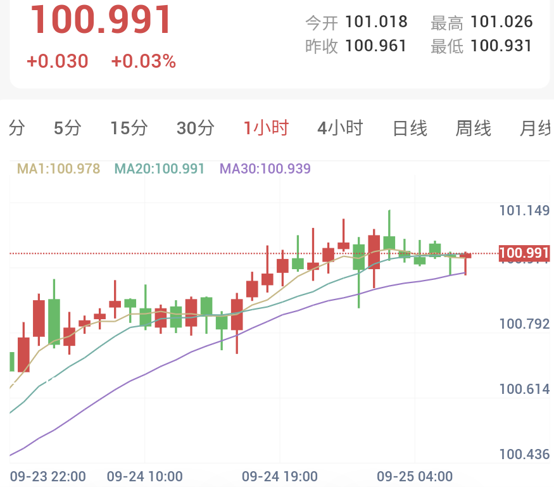
The US dollar and Treasury markets maintained their strength on Thursday.
The US Dollar Index touched an intraday high of 101.39, marking a fresh two-month high. Recent US employment data also remained resilient, with initial jobless claims for the week ending September 19 dropping to 197,000, below market expectations of 201,000, with the prior reading revised to 198,000. Following the data release, the dollar index continued to trade above 101.
US Treasury yields climbed concurrently. The 30-year Treasury yield rose to 5.5016% intraday, the 10-year yield touched 5.2251%, and the 2-year yield hovered near 4.9%.
IV. US Durable Goods Orders and Fedspeak Take Center Stage as US-China Talks Await Market Digestion
Markets will focus heavily on the preliminary US August durable goods orders month-on-month data on September 25, alongside subsequent speeches from Fed officials, including Kansas City Fed President Schmid. Markets will continue to assess whether these inputs alter pricing for the 2026 rate path.
Bilateral US-China meetings also remain in focus, covering trade, artificial intelligence, and other issues. Public reports indicate that certain economic arrangements have been extended, but core issues remain open for future negotiations, leaving potential for continued volatility in the dollar and global risk appetite.
Middle East Attacks Persist, Fed Hawkish Barrage Hits Gold to 1-Week Lows
Published: 2026-09-25 11:05:55