Wangwang Gold Industry

Recommended Gold Trading Platforms 2026·Scratch for Good Luck
Federal Reserve interest rate meeting

2026 FOMC meeting opening time

00day00hour00minute00second

Changes in Interest Rate Decisions and Their Impact

Key interest rates and data

  • Announcement time

    2026-09-17 02:00

  • Current interest rate

    3.75-4%

  • This change

    25

  • Next time announced

    2026-10-29 02:00

  • Next prediction

    3.75-4%

  • Inflation recently

    3.4

Interest rate trends

Fed rate changes and impacts

Resolution timeVariable anchorInterest rate after adjustment
2026-10-2903.75 - 4%
2026-09-17253.75 - 4%
2026-07-3003.5 - 3.75%
2026-06-1803.5 - 3.75%
2026-04-3003.5 - 3.75%
2026-03-1903.5 - 3.75%

Grasp Market Opportunities, Make Accurate Layout Decisions

Fed Decision Preview

  • October 2026 Interest Rate Forecast

  • Forecast for the January 2027 interest rate decision

Overview of recent remarks by Federal Reserve officials

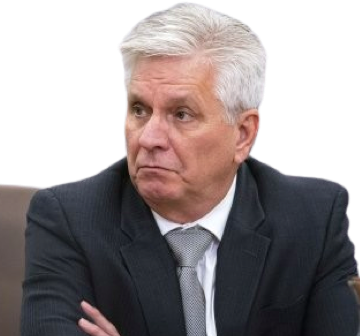
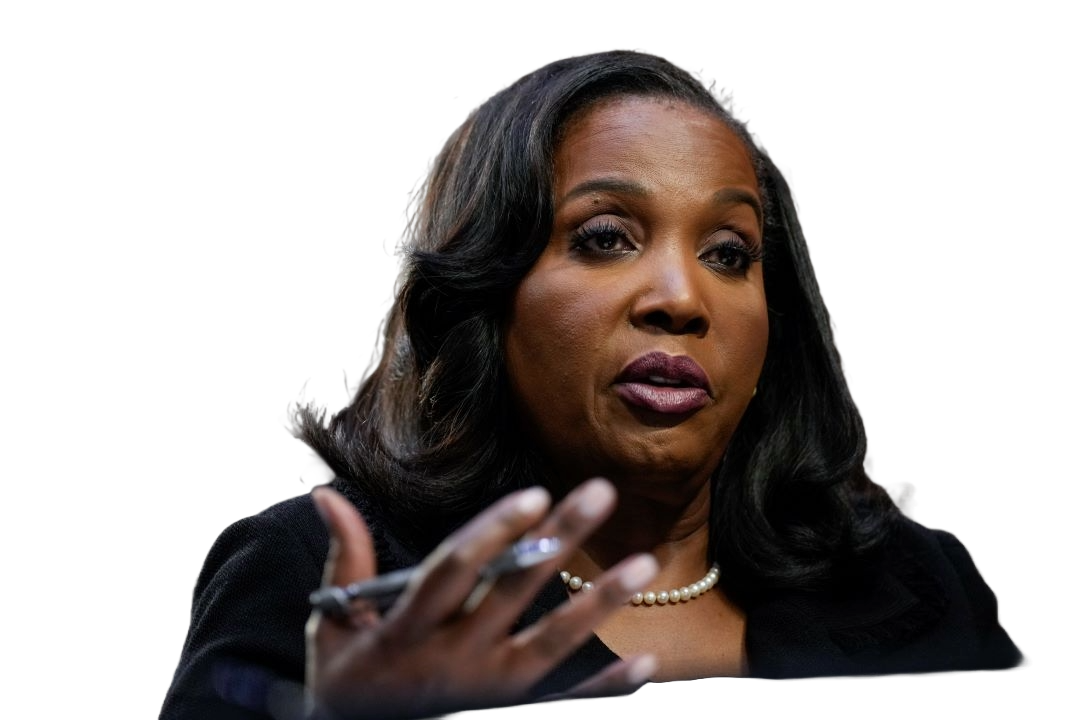
Federal Reserve GovernorWaller

Waller

Federal Reserve Governor

Fed May Need to Hike Rates Soon

Monetary policy is at a "crossroads" and the central bank might need to raise interest rates in the near term. With the military conflict between the U.S. and Iran pushing oil prices higher and inflation running hot for months, sternly staring at inflation until it melts" is simply not an option.

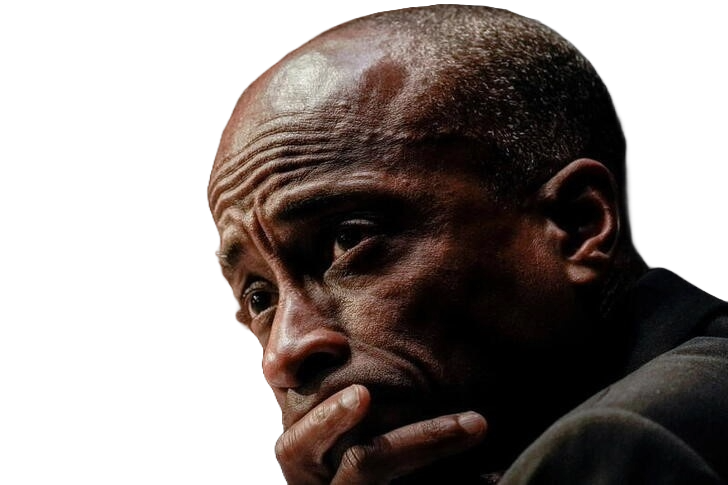
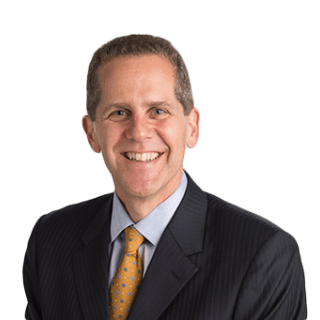
Federal Reserve Vice ChairJefferson

Jefferson

Federal Reserve Vice Chair

Williams: Inflation is Still Heading Down

New York Fed President John Williams said that even though Middle East tensions and AI spending are bumping up prices right now, the bigger picture shows inflation is still cooling off. He believes the Fed can afford to be patient and doesn't need to rush into changing interest rates just because of temporary energy shocks.

President of the Cleveland FedHammack

Hammack

President of the Cleveland Fed

Rate Hikes are Still on the Table

Cleveland Fed President Beth Hammack warned that the central bank's current interest rates aren't doing enough to cool down the economy. She pointed out that tech giants are spending like crazy on AI data centers, paying almost any price for tech inputs, electricity, and insurance, which is keeping inflation sticky. Hammack made it clear that since inflation has been running hot for five years, she won't hesitate to support another rate hike if these price pressures don't ease up.

Fed ChairKevin Warsh

Kevin Warsh

Fed Chair

Think more, speak less.

Vowed to implement sweeping institutional reforms at the Federal Reserve to break the decade-long habit of over-explaining everything to the market. Asserts that the central bank should eliminate forward guidance entirely. Focuses on aggressively shrinking the Fed's balance sheet to suppress and curb inflation.

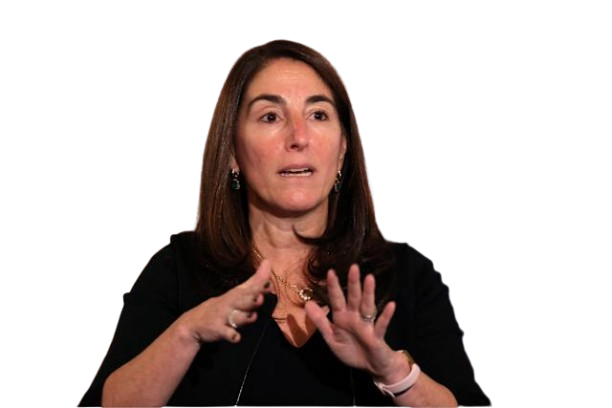
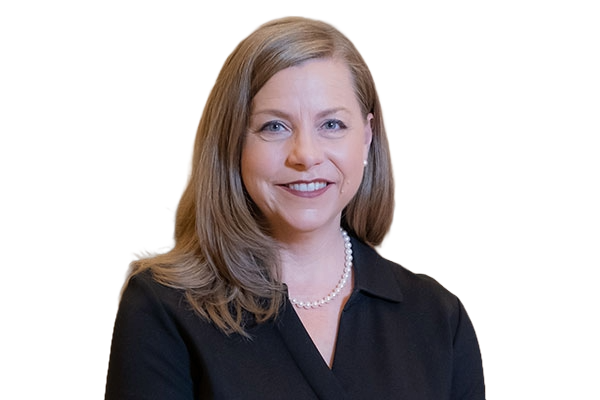
President of the Dallas FedLogan

Logan

President of the Dallas Fed

We Might Need to Hike Rates Later This Year

Logan warned that inflation is taking way too long to get back to the 2% target, seemingly stuck in the mid-2% range instead. She expressed growing concern that current interest rates aren't doing enough to heavy-up on rising prices, making it clear that the central bank might actually need to push rates higher later this year to finish the job.

President of the Minneapolis FedKashkari

Kashkari

President of the Minneapolis Fed

Ditches Rate Cuts and Now Expects a Hike

Massive capital pouring into AI infrastructure and data centers is jacking up borrowing costs across the economy, while lingering Middle East tensions keep energy prices volatile. Kashkari made it clear that with core inflation moving sideways, the Fed will push rates as high as needed if prices refuse to cool off.

President of the Philadelphia FedPaulson

Paulson

President of the Philadelphia Fed

It's Healthy for Markets to Price In Potential Hikes

Philadelphia Fed President Anna Paulson said that while the current level of U.S. interest rates is doing its job to cool down inflation, she thinks it is actually a good thing that investors are bracing for tougher scenarios. Paulson noted it is "healthy" for markets to start pricing in a much longer hold or even further rate hikes as the central bank navigates ongoing economic uncertainty.

Federal Reserve GovernorCook

Cook

Federal Reserve Governor

Ready to Hike Rates If Needed

There was a massive surge in AI spending alongside the oil price spike from the Middle East conflict has put renewed upward pressure on inflation. While she thinks the right move for now is to hold interest rates steady, she warned that she is fully prepared to back another rate hike if inflation doesn't start cooling down soon.

Fed Vice Chair for SupervisionBowman

Bowman

Fed Vice Chair for Supervision

the Fed Might Have to Get Tougher on Rates

Progress on cooling down inflation has hit a bit of a wall, meaning the central bank needs to tread carefully. While she's hopeful that the current surge in energy prices from the Middle East conflict will be temporary, she made it clear that if these oil disruptions drag into the second half of 2026, she wouldn't rule out shifting her stance toward tighter monetary policy to keep prices under control.

Fed GovernorBarr

Barr

Fed Governor

Get Ready for Interest Rates to Stay Put for a While

Interest rates might need to stay right where they are for an extended period. He pointed out that inflation is still stuck notably above the Fed's 2% target, and wild cards like rising oil prices from the Middle East conflict are adding extra risk. Barr made it clear that until he sees solid proof that prices are genuinely cooling down, he is not on board with cutting rates any further.

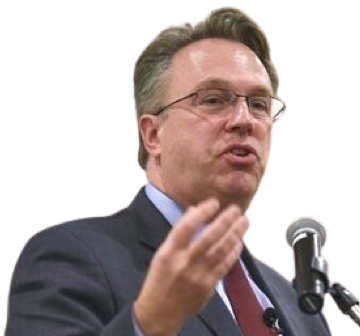
President of the New York FedWilliams

Williams

President of the New York Fed

Monetary Policy Currently "Well Positioned"

Federal Reserve's current monetary policy stance is "well positioned" to sustainably bring inflation back to its 2% longer-run goal. Despite supply chain risks from the Middle East conflict and potential price pressures from the AI investment boom, he expects inflation to edge down in the coming quarters, supporting the decision to maintain interest rates at 3.5% to 3.75%.

Federal Reserve GovernorPowell

Powell

Federal Reserve Governor

Policy Currently in a "Good Place"

Against the backdrop of the energy shock triggered by the war involving the U.S. and Israel against Iran, the Federal Reserve leans toward keeping interest rates unchanged and temporarily "ignoring" the impact of this shock. Raising rates now would not help lower prices; instead, it could cause damage to the economy in the future.

Fed Interest Rate Decision Hot Articles

Fed Headline Article
Fed Rate Cut

Why Gold Always Performs Well When the Fed Cuts Rates

In financial markets, gold is viewed as a vital safe-haven asset, with its price heavily influenced by various macroeconomic factors. The Federal Reserve's monetary policy, particularly its decisions to cut interest rates, usually exerts a significant impact on the gold market.

2026-03-02 15:57:34
Fed Secondary Article
Fed and Silver

The Fed and Silver: How Rate Changes Affect Industrial Demand for Silver

Silver is an important precious metal, but unlike gold, it is used heavily in industry as well as in investment. A large share of silver demand comes from industrial use. The Fed’s monetary policy, especially changes in interest rates, can affect silver demand indirectly by changing economic activity, borrowing costs, and market liquidity. Understanding this link is important for analyzing the silver market and making investment decisions.

2026-03-02 15:57:32
Fed Popular Article
Fed and Gold

Gold Doesn't Care About Interest Rates—It Cares About "Expectations"

In live markets, traders frequently witness an apparent paradox: the Federal Reserve announces a rate hike—which conventional wisdom dictates is bearish for gold—yet gold prices surge.

2026-01-15 11:35:39
4.  Why the Same Federal Reserve Rate Resolution Impacts Gold and Silver Differently
2026-01-15 11:35:38
5.  
2025-12-16 17:39:51

Federal Reserve Interest Rate Report

lucky gold

Federal Reserve September 2026 Meeting Minutes

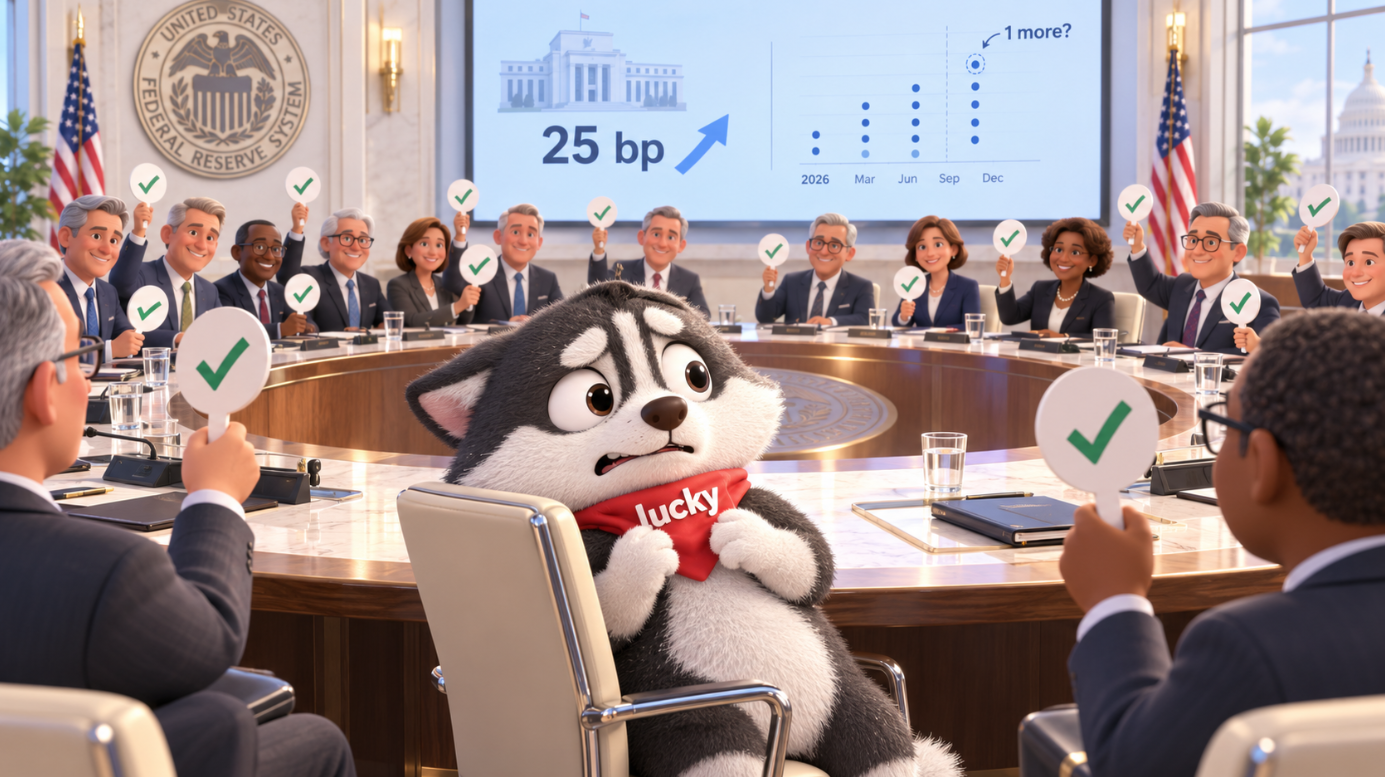
On September 16, 2026, the Federal Open Market Committee (FOMC) concluded its two-day policy meeting, voting 12-0 to raise the target range for the federal funds rate by 25 basis points from 3.50%-3.75% to 3.75%-4.00%. The official statement noted that economic activity continues to expand at a solid pace, domestic spending demonstrates resilience, productivity growth remains robust alongside sound capital investment, and employment gains have largely kept pace with labor supply; however, inflation remains elevated, and this action aims to return inflation to the 2% objective in a more timely manner. This marks the first policy rate adjustment under Chair Kevin Warsh and formally translates several months of mounting hawkish posture into concrete policy action.Note: The formal FOMC meeting minutes will be published on October 7; this document represents a real-time summary based on official post-meeting releases.I. Unanimous Hike: Transitioning from Hawkish Dissent to Committee ConsensusAt the June meeting, the FOMC unanimously held the target range unchanged at 3.50%-3.75%; in July, although the pause was maintained, the vote shifted to 9-3, with Beth Hammack, Neel Kashkari, and Lorie Logan explicitly calling for an immediate 25 bps rate hike. By September, this view evolved into the unified stance of the entire Committee. In the press conference, Warsh explained that recent trends in payroll additions, private sector income, and business capital investment had all improved, while business credit flows remained solid. Crucially, he noted it was 'difficult to characterize broad financial conditions as restrictive,' a perspective widely endorsed across the FOMC. Therefore, this action serves as a recalibration of policy restraint: with the economy resilient and broad financial conditions remaining unrestrictive, the Fed opted to withdraw an additional degree of accommodation.II. Labor Is Not the Primary Constraint; Policy Center Gravity Pivots to InflationStability across the labor market provided the essential foundation enabling the Fed to tighten policy with confidence. Warsh pointed out that the unemployment rate hovers near 4.1%, job openings and average weekly hours have increased, and initial jobless claims remain consistent with full employment, leaving the maximum employment mandate in overall 'good shape.' In contrast, inflation pressures stand out prominently. Warsh underscored that US inflation has run above target for more than five years, stating 'inflation is too high and has been too high for too long.' Based on recent CPI and PPI readings, August headline PCE inflation is estimated near 3.6% year-over-year with core PCE at roughly 3.2%; concurrently, annualized price increases across several key categories over 6-month and 12-month spans remain above 3%. His previously established benchmark was that further patience required clear evidence that underlying inflation was moving 'unambiguously and fast enough' toward 2%; the Committee determined in September that this threshold was not satisfied.III. Four Major SEP Revisions: Higher Growth, Lower Unemployment, Higher Inflation, and Higher Terminal RatesThe Summary of Economic Projections (SEP) released alongside the statement provided further context for the decision. The median projection for 2026 real GDP growth was revised upward from 2.2% in June to 2.3%, and 2027 was raised from 2.3% to 2.4%; the 2026 unemployment rate forecast was revised downward from 4.3% to 4.1%, with 2027 similarly lowered to 4.1%. This reflects a more upbeat assessment of economic activity and employment than in June. Conversely, inflation projections deteriorated in tandem: 2026 PCE inflation was lifted from 3.6% to 3.7%, core PCE from 3.3% to 3.4%, while 2027 PCE inflation remained projected at 2.3%. Consequently, the SEP outlined an unambiguous combination: stronger-than-expected economic growth, sturdier employment, and more entrenched inflation. Under these conditions, the Fed judged that the economy can comfortably bear higher interest rates, allowing policy to lean decisively toward containing price pressures.IV. A More Hawkish Dot Plot: Another 25 bps Hike in 2026 with Elevated Rates Extending into 2027Compared with the 25 bps rate increase itself, the updated dot plot carries far greater market significance. The September SEP sharply revised the median federal funds rate projection for year-end 2026 upward from 3.8% in June to 4.1%, the 2027 projection from 3.6% to 4.1%, and 2028 from 3.4% to 3.9%. With the current target range midpoint situated at approximately 3.875%, the 4.1% year-end median implies another 25 bps rate hike before the close of 2026. More critically, the 2027 median rate forecast holds flat at 4.1%, underscoring that the baseline trajectory does not anticipate rapid pivot toward rate cuts, but rather 'another potential hike this year followed by an extended period with policy rates above 4%.' Market focus has decisively transitioned from July's question of 'will they hike again' to 'how many more hikes remain and how long will restrictive rates persist.'V. Market Implications: The Primary Shock Stems from 'Higher for Longer'Because the 25 bps rate hike had been largely anticipated, post-meeting repricing was driven by the more hawkish SEP and Warsh's characterization of broad financial conditions. Short-end Treasury yields pushed higher, the US Dollar Index strengthened, and bullion faced downward pressure, reflecting recalibrated investor expectations for terminal policy rates. For non-yielding assets such as gold, the dominant headwind is not the single rate hike delivered in September, but the Fed's systematic upward revision to the future policy rate trajectory, signaling that rates above 4% may persist well into 2027. Going forward, inflation remains the paramount variable. Should core inflation metrics and commodity prices remain resilient, the threshold for a second rate hike this year will decline further; conversely, only a broad-based, persistent, and sufficiently rapid deceleration in underlying inflation would prompt the Fed to moderate its tightening pace.Conclusion and OutlookThe September 2026 FOMC meeting marks the formal transition of Warsh-era monetary policy from a 'hawkish pause' to 'active tightening.' Moving from a unanimous hold in June, to three hawkish dissents in July, and finally to a 12-0 unanimous rate hike in September, Committee consensus regarding inflation risks has solidified. The true essence of this meeting extends beyond the 25 bps rate hike to the core logic articulated in the SEP: stronger growth, lower unemployment, and higher inflation warrant a higher policy rate. Under the latest dot plot, another 25 bps hike this year constitutes the median view, while policy rates holding at 4.1% through year-end 2027 reaffirm that 'higher for longer' has reclaimed center stage as the dominant policy framework. The core question for markets going forward is crystal clear: can inflation cool fast enough, and will forthcoming data prove sufficient to dissuade the Federal Reserve from delivering its next rate increase.Sources: Federal Reserve FOMC Statement, Summary of Economic Projections, Chairman Warsh Press Conference, September 16, 2026; Federal Reserve H.15.


lucky gold

Fed September Meeting Preview

Fed September Meeting PreviewThe Federal Open Market Committee (FOMC) convenes on September 15–16, with the rate decision scheduled for release on September 16 at 2:00 PM EDT (September 17 at 2:00 AM Beijing time), followed by the Chair's press conference at 2:30 PM. The Fed will also release updated Summary of Economic Projections. The current target range for the federal funds rate stands at 3.50%–3.75%.Unlike the sharp division observed prior to the July meeting, recent CPI, PPI, employment, and crude oil figures have tipped the scale decisively toward the hawkish camp. The baseline expectation is a 25 bps rate hike; however, the market's primary sensitivity lies not in this 25 bps move itself, but in whether Chair Kevin Warsh signals the necessity of a second hike before year-end.1. Rate Decision Preview: 85% Hike Probability, September Poised for Year's First HikeOn July 29, the FOMC held rates steady in a 9–3 vote, with three dissents favoring an immediate 25 bps increase. The policy statement emphasized that inflation remained above the 2% target, driven partly by supply-side energy shocks.Short-term interest rate futures currently price in an approximate 85% probability of a 25 bps hike, up from roughly 70% prior to the CPI release. Pricing has also begun incorporating the likelihood of an additional move in December.Warsh established a clear threshold during his August Jackson Hole address: the Fed can only be assured when underlying inflation is returning toward 2% "clearly and at a sufficiently rapid pace." Recent data fails to meet this condition, making a pause harder to justify. The meeting entails two distinct layers: first, whether to hike in September (largely consensus); second, whether further tightening follows, which will be dictated by the dot plot and press conference tone.2. Resurgent Inflation: Core CPI, PPI, and Energy Generate Triple PressuresAugust CPI rose 0.4% MoM and 3.4% YoY. Core CPI increased 0.3% MoM (above the 0.2% consensus) and 2.4% YoY, with gasoline surging 3.9% MoM and the energy index advancing 2.1%.Upstream price pressures were more pronounced: final demand PPI rose 0.4% MoM and 5.4% YoY, with goods prices jumping 1.1%, indicating that raw material and energy costs continue to pass through to production pipelines. Meanwhile, escalating Middle East conflict pushed crude back above $100 per barrel, heightening the risk of inflation persistence.On the labor front, August non-farm payrolls added 162,000 jobs with the unemployment rate steady at 4.1%, accompanied by an upward revision of 55,000 across the prior two months. The labor market has not deteriorated sufficiently to warrant a pause.3. Internal FOMC Divisions: Debate Pivots from "Whether to Hike" to "How Many"With three dissents already recorded in July and two months of hot data reinforcing the hawkish thesis, internal policy deliberations have shifted:• Hawks: Argue inflation risks outweigh labor market risks, advocating an immediate hike while keeping a December follow-up firmly on the table.• Centrists: Support a hike but prioritize incoming data validation, resisting pre-commitments to sequential tightening.• Doves: Contend that supply-driven commodity shocks should not be answered mechanistically with tighter policy, focusing instead on PCE components and policy transmission lags.For Warsh, pausing after hot CPI, firm PPI, solid jobs, and climbing oil prices would trigger severe credibility scrutiny. The updated dot plot serves as the critical anchor: if the median end-2026 funds rate forecast remains near 3.8%–3.9%, it will be read as a "one-off calibration"; a shift toward 4.1% would confirm growing consensus for a subsequent year-end hike.4. Heightened White House Pressure: Independence Under the SpotlightFormer President Donald Trump publicly reiterated ahead of the meeting that the US should enjoy the "lowest interest rates globally," linking trade policy to monetary easing. While the White House simultaneously pays lip service to Fed independence, the political friction remains acute just weeks ahead of midterm elections. A hike invites public criticism from Washington, while a pause risks accusations of yielding to political pressure.The press conference will center on four key signals: ① Whether the hike is framed as a "calibration" rather than a new tightening cycle; ② Whether disinflation progress is described as "not fast enough"; ③ The assessment of persistence regarding energy and tariff shocks; ④ Explicit avoidance of pre-commitments for December.Scenario Analysis and Summary• Baseline Scenario (Highest Probability): 25 bps hike with optionality preserved for future tightening; US dollar and short-term yields firm, gold faces initial downside before reacting to policy nuance.• Hawkish Scenario: 25 bps hike accompanied by a dot plot signaling a December follow-up; yields and dollar rally further, pressuring risk assets.• Dovish Surprise: Rates held steady with emphasis on PCE and supply-side dynamics; bond yields fall, dollar softens, and gold rallies, but inflation credibility is challenged.Baseline expectation: A 25 bps hike to a target range of 3.75%–4.00%. Even with a hike priced in, the dot plot distribution, vote split, and Warsh's communication will generate notable cross-asset volatility.

lucky gold

July 2026 Federal Reserve Meeting Minutes

On July 29, 2026, the Federal Open Market Committee (FOMC) concluded its second monetary policy meeting chaired by newly appointed Chairman Kevin Warsh.Against a complex backdrop of escalating US-Iran conflict—marked by attacks on US vessels in the Middle East and President Trump's vows of retaliation—and persistent inflation pass-through, the FOMC voted 9-3 to keep the target range for the federal funds rate unchanged at 3.50% to 3.75%.Although the committee paused rate adjustments, three policymakers cast dissenting votes favoring an immediate 25-basis-point rate hike. Coupled with Chairman Warsh's firm rejection of any "soft inflation target" during the press conference, financial markets fully relinquished expectations of near-term monetary easing.I. Monetary Policy Action and Hawkish DissentsThe meeting underscored the rapid emergence and dominant influence of hawkish factions within the Federal Reserve when confronting supply-side inflationary shocks.Resolution DecisionThe FOMC passed the decision to maintain rates at 3.50% to 3.75% by a 9-3 vote while maintaining its balance sheet policy to ensure ample reserve balances across the banking system.Three Official Dissents Advocating a 25-Basis-Point Rate HikeDissenting members included Cleveland Fed President Beth M. Hammack, Minneapolis Fed President Neel Kashkari, and Dallas Fed President Lorie K. Logan. All three argued that inflation had remained above target for too long with heightened upside risks, advocating an immediate 25-basis-point increase in the federal funds rate target to 3.75%–4.00%.II. Federal Reserve ObjectivesThe Fed maintained concise macroeconomic language in its official statement, but Chairman Warsh provided deeper context regarding inflation dynamics and structural economic shifts during the press conference.Rejection of Soft Inflation TargetsThe official statement noted that inflation remains elevated due to supply-side energy shocks, reiterating a firm commitment to restoring price stability.Warsh forcefully pointed out that over five years of elevated inflation led some market participants to mistakenly assume a "soft or stealth inflation target" above 2%. Clarifying on behalf of the committee, he stated that under his tenure there is no soft target; the target remains strictly 2%. Five consecutive years of overshooting cannot be remedied in nine weeks or through minor single-month declines, and the Federal Reserve will not waver.III. Warsh's Governance Paradigm: Abandoning Forward GuidanceMarking Warsh's second chaired meeting, structural reforms to central bank governance are accelerating.Teaching Markets to Watch Data Rather Than the UmpireWarsh noted that over the 42 days between meetings, abandoning forward guidance produced noticeable results, including one of the largest spikes in real Treasury yields in two decades. He endorsed this shift, emphasizing that markets are re-pricing assets based on genuine economic data rather than parsing central bank phrasing, noting that the central bank should not always sit at the center of financial markets.Progress Across Five Special Task ForcesFive task forces established in June—covering communication, balance sheet reduction, data sourcing, AI and productivity, and the inflation framework—remain on schedule, with preliminary framework proposals expected in autumn.IV. Market Reactions and Asset PerformanceFollowing the announcement, the decision to hold rates steady prompted short-term safe-haven inflows and short-covering rallies, as extreme market rumors had speculated an immediate rate hike prior to the release.Spot Gold (XAUUSD)In price action, spot gold rose 0.4% to $4,080.38 per ounce, while August gold futures advanced 1.1% to $4,078.00 per ounce. The Fed's pause triggered short covering among rate bears, though elevated energy prices and lingering September rate-hike risks capped upside momentum.US Dollar Index (DXY)The US Dollar Index slipped 0.49% to 100.92. Because the Fed refrained from an aggressive hawkish hike, the dollar pulled back modestly from recent highs.Adjustment in Rate Hike ProbabilitiesCME FedWatch data following the resolution showed market expectations for a September rate hike adjusting from 81% prior to the meeting down to 64.1%. Traders now await upcoming June PCE inflation data and Q2 GDP prints for further policy direction.Geopolitical Black Swan EventsMiddle East hostilities spilled into Damietta Port, Egypt, following a drone attack on a US-flagged LNG tanker, prompting President Trump to vow retaliatory actions against Iran. Elevated Brent crude prices remain a primary headwind for both gold bulls and the Federal Reserve.V. Summary and OutlookThe July 2026 FOMC meeting showcased a transformed Federal Reserve under Kevin Warsh—one characterized by a complete removal of forward guidance, strict data dependency, and zero tolerance for inflation. From easing cuts in late 2025 to geopolitical oil shocks and tariff lag effects in mid-2026, the central bank has closed the door on rate reductions. Three dissenting votes favoring immediate rate hikes signal that the institutional balance has tipped firmly toward inflation containment. Heading into the mid-September meeting, incoming PCE reports and Middle East developments will determine whether the Fed resumes rate hikes. For non-yielding assets like gold, markets will continue to engage in an intense tug-of-war between geopolitical safe-haven demand and the persistent weight of higher-for-longer interest rates.

lucky gold

July Fed Meeting Outlook

The Federal Open Market Committee will convene its monetary policy meeting from July 28 to 29 US Eastern Time, announcing its interest rate decision during the early hours of July 30 Beijing Time. The target range for the federal funds rate currently stands at 3.50% to 3.75%.Just two weeks ago, mild June CPI figures prompted broad market expectations that the Federal Reserve would hold rates steady. However, subsequent geopolitical escalation in the Middle East driving up primary energy commodities, the implementation of new global tariffs, and a surge in artificial intelligence infrastructure investment are rapidly transforming the inflation narrative.Marking the second FOMC meeting chaired by new Fed Chairman Kevin Warsh, this rate decision has evolved from a routine event into the most contentious and uncertain rate political showdown of the second half of 2026.Decision Outlook and Market Divergence: Hike Bets Surge as Institutions and Options DisconnectMarket Pricing: Rate Hike Probability Spikes from 10% to Nearly 38%Following the release of June CPI data, futures markets priced the probability of a 25-basis-point rate hike in July down to near 10%. However, as external shocks compounded, CME FedWatch and LSEG data as of July 27 indicate that the probability of holding rates unchanged stands at roughly 63.7%, while the implied chance of a direct 25-basis-point hike has climbed sharply to 36.3%. Regarding forward trajectories, market pricing for a September rate hike has surged to 80%, fully discounting a cumulative 50 basis points of tightening by January 2027.Wall Street Consensus vs. Derivatives Market DisconnectIn stark contrast to aggressive market pricing, buy-side and sell-side economists exhibit unified caution. A Reuters poll of 104 economists shows the vast majority expect the Federal Reserve to keep interest rates unchanged this week. This profound disconnect between economist expectations for a pause and trader positioning against rate hike shocks highlights market confusion following Warsh's abandonment of forward guidance.Commodities Breach $100 as Tariffs and AI Spending Fuel Inflationary ConcernsAlthough June CPI slowed to 3.5% year-over-year with core CPI flat month-over-month, signaling a temporary cooling, escalating Middle East conflicts pushed benchmark energy commodities past $100 per barrel intraday—a surge of roughly 25% since the June FOMC meeting. Upstream material costs are rapidly transmitting downstream into vehicle fuels and industrial freight.Concurrently, the Trump administration announced new tariffs ranging from 10% to 12.5% on 60 countries on July 24, replacing a prior framework struck down by the Supreme Court and exacerbating re-inflation risks for imported goods. Furthermore, elevated capital expenditure in AI models and infrastructure continues to drive demand for power, copper, and tech equipment, injecting added aggregate demand into the economy.Analysts at Citigroup and other institutions point out that supply-driven price shocks should not automatically trigger monetary tightening. Nevertheless, with long-term inflation remaining above the 2% target, a hawkish pause or dovish inaction risks unanchoring inflation expectations.Hawks vs. Doves Battle Within the FOMCInternal divisions within the FOMC are widening significantly, splitting policymakers into three distinct camps.The hawkish faction—led by Dallas Fed President Lorie Logan, Cleveland Fed President Beth Hammack, and Minneapolis Fed President Neel Kashkari—advocates for a rate hike and is prepared to dissent. They argue that inflation risks far outweigh employment risks, advocating a modest hike to solidify disinflationary gains.The dovish and wait-and-see group—represented by New York Fed President John Williams and mainstream Wall Street institutions—favors maintaining current rates through September. They believe June's core inflation slowdown and labor market stabilization afford valuable time to observe incoming data before acting.Core policymaker Chairman Kevin Warsh maintains a zero-tolerance stance toward inflation, having discarded forward guidance in favor of real-time data-driven decision-making.Asset Class OutlookThe July FOMC resolution coincides with the heaviest week of the Q2 corporate earnings season, with roughly one-third of the S&P 500 market cap reporting, including AI giants like Microsoft, Meta, Amazon, and Apple.For Treasuries and the US Dollar, the 10-year Treasury yield recently breached 4.71%, while the 30-year yield touched 5.18% to hit a near two-decade high. A hawkish pause or multiple dissents would keep Treasury yields elevated and support the US Dollar Index against more dovish central bank currencies.For gold, geopolitical friction and surging commodities offer safe-haven and inflation-hedge support, but elevated real yields and dollar strength pose major headwinds. Should the Fed reinforce expectations of late-year hikes, gold prices will face short-term pressure, testing key support zones at $4,000 and $3,900 per ounce.Summary and Future OutlookThe July 2026 FOMC meeting marks a critical turning point in the Federal Reserve's policy paradigm transition. Intertwined with commodity costs, tariffs, and external political friction, holding rates steady no longer signals tranquility, but rather a hawkish pause masking underlying pressures for future tightening. For investors navigating the unguided Warsh era, attention must focus not only on the rate decision itself, but on press conference commentary regarding supply shocks and the degree of internal voting division.

lucky gold

Minutes of the Federal Reserve's June 2026 Meeting

On June 17, 2026, the Federal Reserve held its first Federal Open Market Committee (FOMC) meeting chaired by the newly appointed head, Kevin Warsh. The Committee voted unanimously to keep the target range for the federal funds rate unchanged at 3.50%–3.75%. This meeting carried a strong "epoch-making" tone: the Fed not only drastically trimmed its policy statement and completely abandoned "forward guidance," but it also unleashed a heavy hawkish signal in its latest dot plot, hinting at potential rate hikes later this year.I. Monetary Policy Action and the Brand-New Communication FrameworkThis meeting brought major overhauls to policy execution and institutional operations:Interest Rate Decision (12–0 Unanimous Pass): The FOMC decided by an overwhelming 12–0 vote to maintain the current interest rate level at 3.50%–3.75%. Meanwhile, the Committee reaffirmed its policy of maintaining ample reserves in the banking system.A Complete Makeover of the Policy Statement: The first policy statement under Warsh’s leadership was significantly shortened and simplified, removing outdated and redundant phrasing. Crucially, all forward guidance regarding the future path of interest rates was entirely deleted. During the press conference, Warsh emphasized that forward guidance is no longer suited for the current policy environment and that the market should focus more on actual economic data rather than relying on Fed guidance.Launching Five Special Task Forces: To comprehensively review the Fed's core business, Warsh announced the formation of five special task forces. They will focus respectively on: 1) Fed communication mechanisms; 2) balance sheet policy (assessing the ample reserves regime and asset structure); 3) the use of data sources; 4) the impact of new technologies like AI on productivity and employment; and 5) tackling inflation.II. Assessment of Economic Conditions and Outlook (SEP Update)Faced with a complex and tangled situation, the Fed maintained a steady outlook on the macroeconomy but showed significantly heightened concern over inflation:Stubbornly High Inflation: The statement clearly pointed out that, driven by supply shocks in specific sectors like energy, inflation remains "elevated" relative to the long-term 2% goal. According to the latest Summary of Economic Projections (SEP), the median expectation for PCE inflation in 2026 is as high as 3.6%, and it is not expected to cool down to 2.3% until 2027. To this end, a rare and deeply determined pledge was added to the statement: "The Committee will deliver price stability."Steady Economy and Employment: Despite high uncertainty brought on by the Middle East conflict, economic activity has continued to expand at a solid pace, supported by strong capital investment and productivity growth. The SEP forecasts median real GDP growth at 2.2% for 2026 and 2.3% for 2027. The labor market remains stable, with the median unemployment rate projection for 2026 holding at 4.3%.III. Policy Considerations and the Hawkish Reversal of the "Dot Plot"The biggest market shock from this meeting came from a complete U-turn in dot plot expectations:Surge in Rate Hike Expectations for the Year: SEP data showed that officials' median forecast for the federal funds rate at the end of 2026 skyrocketed from its previous low to 3.8% (which is above the current 3.75% upper limit), and the forecast for the end of 2027 landed at 3.6%. Out of 19 officials, 9 expect further rate hikes will be necessary by the end of this year.The Chairman Leads by Refusing to Submit a Dot: In an extremely rare move, Warsh publicly confirmed at the press conference that he did not submit his own interest rate forecast dot, stating that he found it "unhelpful" for current policy execution. He hinted that the format of the dot plot could face major adjustments or even be completely abolished in the future.IV. Market Reaction and Political DynamicsFollowing the announcement, financial markets were suppressed by the hawkish stance:Due to Warsh’s aggressive anti-inflation posture and the higher-than-expected dot plot hikes, spot gold plummeted during yesterday's trading session (June 18) from above the 4,400 mark to close at 4,256.88.At the same time, the three major Wall Street stock indices all closed down over 1%. The S&P 500 fell 1.19%, the Nasdaq dropped 1.32%, and the Dow Jones Industrial Average slid 0.96%. Market traders have completely given up on recent rate cut fantasies and begun pricing in the Fed's next rate hike.Trump's Unexpected Compromise: Although US President Donald Trump had previously demanded aggressive rate cuts from the Fed (under former Chair Jerome Powell), his attitude was surprisingly mild following this hawkish decision. Speaking from France while attending the G7 summit, Trump noted that while keeping interest rates so high was "incredible," the Fed was now captained by "a very good man," adding that he would be "guided by what he wants."ConclusionChairman Warsh's debut set a brand-new tone for the Federal Reserve: pragmatic, streamlined, and iron-fisted against inflation. By scrapping forward guidance and setting up the five new task forces, Warsh is trying to break the over-reliant relationship that has formed between the market and the Fed over recent years. Confronted with a stubborn 3.6% inflation forecast, the Fed's policy center of gravity has fully shifted away from "precautionary rate cuts" toward a "hawkish defense" against an inflation rebound. For investors, the era of blindly betting on rate cuts is over; the market must now adapt to a new trading epoch dictated by real economic data—one where the Fed stands ready to pull the trigger on rate hikes at any moment.

lucky gold

Fed June Meeting Preview: The New Chair's Debut and a Communication Overhaul

The Federal Open Market Committee (FOMC) will convene for its policy meeting on June 16–17 Eastern Time, with the interest rate decision and the latest Summary of Economic Projections scheduled for release on June 17. This will be the first monetary policy meeting hosted by the newly appointed Chair, Kevin Warsh, making its importance stretch far beyond a routine rate review. The target range for the federal funds rate currently stands at 3.50%–3.75%. Factoring in the latest non-farm payrolls and CPI data, the market widely expects a hold in June. However, the core suspense lies in two questions: What kind of policy signal will Warsh send? And is the Fed's communication framework about to undergo a historic overhaul?I. Interest Rate Decision: A Hold Is a Foregone Conclusion, but a "Hawkish Pause" Becomes the Baseline ScenarioLabor Market Resilience: May non-farm payrolls showed an increase of 172,000 jobs, coming in significantly higher than expected, while the unemployment rate held steady at 4.3%. With the data for the previous two months upwardly revised by a combined 93,000 jobs, the sheer strength of the labor market signals that the Fed faces zero immediate pressure to deliver early rate cuts to shore up the economy.Energy-Driven Inflation Tensions: On the inflation front, the May CPI rose 0.5% month-over-month, pushing the year-over-year print up to 4.2% (higher than April's 3.8%). Energy prices jumped 3.9% month-over-month and plummeted a staggering 23.5% year-over-year, with gasoline prices skyrocketing 40.5% annually. However, core CPI remained relatively tame, ticking up 0.2% month-over-month (down from the previous 0.4%) and hitting 2.9% year-over-year (a minor increase from April's 2.8%). This suggests that the current flare-up in inflation is primarily a supply-side phenomenon driven by energy shocks, rather than a total breakdown into a core services and wage-price spiral.Rate Hike Bets Linger: According to the CME FedWatch Tool, following the CPI release, the market still prices the probability of a rate hike in June and July below 2%. However, expectations for a hike later in the year persist, with the probability of a December hike remaining well above 60%. All in all, the most probable outcome of this meeting is an unchanged policy rate paired with a distinctly more aggressive tone—the quintessential "hawkish pause."II. The New Chair's Debut: Warsh Is the Ultimate Wild CardWarsh's debut FOMC meeting since taking office is the absolute centerpiece of the month. During his Senate confirmation hearing in April, he made his stance crystal clear, stating, "Unlike many of my past and present colleagues, I do not believe in forward guidance." This philosophy has put the bond market on high alert.Potential changes currently being debated by market participants include:Shortening the FOMC statement to minimize official policy steering.Abolishing the interest rate dot plot—a tool that has served as the core anchor for market expectation management since Ben Bernanke introduced it in 2012.Reducing the frequency of the post-meeting chair press conferences.III. Quantitative Tightening: The Crucial Structural VariableIn the eyes of institutions like PIMCO, the trajectory of the Fed's balance sheet is a far more critical variable than any adjustment to its communication style.The Fed's balance sheet currently hovers around $6.7 trillion, down significantly from its 2022 peak of $9 trillion. Warsh has previously stated that further balance sheet reductions could run parallel with interest rate cuts. Dan Ivascyn, Group CIO at PIMCO, emphasized:"Balance sheet runoff has profound implications for the shape of the yield curve and the performance of bonds across different maturities. This carries significantly more weight than changes in communication style or fine-tuning forward guidance."Summary and OutlookThe core narrative of the June Fed meeting is no longer about the rate decision itself—a hold is a locked-in certainty. The genuine suspense centers on how newly appointed Chair Kevin Warsh will reshape the Fed's communication framework in his debut performance. Will the dot plot hint at upcoming rate hikes? And how will the path for the $6.7 trillion balance sheet unfold?Against a tangled backdrop of labor market resilience, energy-driven inflation, and a simmering conflict in the Middle East, investors are bracing for a Federal Reserve that is bound to be more unpredictable in its communication and potentially more hawkish in its policy signals. For market participants, every single phrase and every pause from Warsh could easily become a fresh catalyst for market volatility.